Guide2 min readDated by the event covered
Gulf AI data centres and fibre routes: a 2026 buyer's guide
Gulf AI campuses kept growing in 2026 while the regional war stalled subsea cable work and pushed operators towards overland routes. How that shapes demand for network hardware.
InTechnologies
guide · data-centre · telecom · ai-infrastructure
On 30 September 2026 the Saudi AI company Humain set out its build plan: 250 MW of data-centre capacity online by the end of 2026, 1.7 GW in 2027, about 3 GW by 2030 and about 6 GW by 2034. Its chief executive, Tareq Amin, put the typical cost of AI data-centre capacity at USD 10 million to 12 million per megawatt and said that most of the capital goes into IT equipment, including GPUs. In the UAE, Mubadala's chief executive said in December 2025 that the first 200 MW phase of Stargate UAE, a 1 GW cluster being built by G42's Khazna Data Centers with OpenAI, Oracle, NVIDIA, Cisco and SoftBank inside a 5 GW UAE–US AI campus, would be ready in the third quarter of 2026. The US had authorised G42 to buy the equivalent of up to 35,000 NVIDIA GB300 chips.
Connectivity under strain
The regional war changed the connectivity picture in 2026. In March, contractors on the 2Africa Pearls extension issued a force majeure notice and stopped work in the Gulf; much of the cable had been laid but several landing stations were not yet connected. Rest of World reported that about 60 cable-repair ships operate worldwide and that none could safely reach the region's maritime chokepoints while fighting continued. Operators have responded with overland projects: STC's SilkLink, a USD 800 million, 4,500 km route through Syria with a first phase expected within 18 to 24 months; the STC and Ooredoo SONIC link between Saudi Arabia and Oman; WorldLink, a hybrid route from the UAE through Iraq to Turkey; and a Zain Omantel corridor from Oman through Saudi Arabia to Egypt. Ooredoo's 720 Tbps Fibre in Gulf subsea system, connecting the GCC states and Iraq, is expected in late 2027.
For hardware, this means two kinds of demand running at once. Inside the campuses, AI clusters need high-radix 800G and, increasingly, 1.6T switching, plus large volumes of short-reach optics. Between sites, the shift to terrestrial and diverse routes increases demand for routers with coherent ZR and ZR+ pluggables, DWDM line systems and the spares to keep long overland spans running when repair times are uncertain.
Humain itself named the risk that an escalation of the war could deter global technology companies, and that a decline in global appetite for AI computing could slow demand. Plans should be built on confirmed, funded phases rather than headline gigawatts.
What it means for buyers
Treat regional capacity announcements as signals of competition for the same constrained items: GPUs, 800G optics and coherent modules. Order long-lead networking items as soon as a phase is funded, specify route-diverse interconnects with the optics and licences for each path, and hold more spares than usual for sites that depend on a single international route. Confirm export-control status early for advanced AI hardware, since large GPU shipments to the region have required US authorisation. InTechnologies can source data-centre switching, routing and optics for Gulf projects.
Sources
- 01Humain plans a 1.7 GW Saudi datacenter build next year2026-09-30
- 02Stargate UAE's first phase to be completed in third quarter of 20262025-12-05
- 03War halts work on submarine cable link in the Persian Gulf2026-03-16
- 04Gulf states race to build overland data cables to Europe as war threatens submarine routes2026-03-11
Related in the catalog
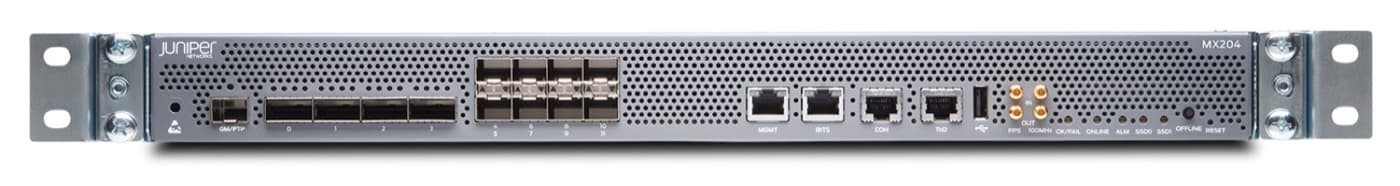
Juniper Networks MX204 Universal Routing Platform
Compact 1U MX Series edge router with 400 Gbps capacity, 4× QSFP28 and 8× SFP+ ports